How can I compare different loan options? – As How Can I Compare Different Loan Options to Find the Best Fit for My Needs? takes center stage, this opening passage beckons readers with casual formal language style into a world crafted with good knowledge, ensuring a reading experience that is both absorbing and distinctly original.
The content of the second paragraph that provides descriptive and clear information about the topic.
Loan Features Comparison

When comparing different loan options, it’s essential to consider various features to make an informed decision. These features include interest rates, loan terms, fees, and repayment options. Understanding these elements will help you determine the best loan option that aligns with your financial situation and goals.
Interest Rates
Interest rates represent the cost of borrowing money. They are typically expressed as an annual percentage rate (APR), which includes both the base interest rate and any additional fees or charges. Comparing APRs allows you to determine which loan option offers the lowest borrowing cost.
Loan Terms
Loan terms refer to the duration of the loan. The term can range from short-term loans (e.g., payday loans) to long-term loans (e.g., mortgages). Choosing a loan term that aligns with your repayment capacity and financial goals is crucial.
Fees
Lenders may charge various fees associated with loans, such as origination fees, closing costs, and late payment fees. These fees can add to the overall cost of borrowing and should be carefully considered when comparing loan options.
Repayment Options
Different loans offer varying repayment options. Some loans require fixed monthly payments, while others allow for flexible repayment schedules. Choosing a repayment option that suits your budget and financial situation is essential to avoid potential payment difficulties.
| Feature | Loan Option A | Loan Option B | Loan Option C |
|---|---|---|---|
| Interest Rate (APR) | 5.99% | 6.49% | 7.25% |
| Loan Term | 36 months | 48 months | 60 months |
| Origination Fee | 1% | 2% | 3% |
| Closing Costs | $500 | $750 | $1,000 |
| Repayment Options | Fixed monthly payments | Flexible repayment schedule | Balloon payment at the end |
Loan Cost Analysis
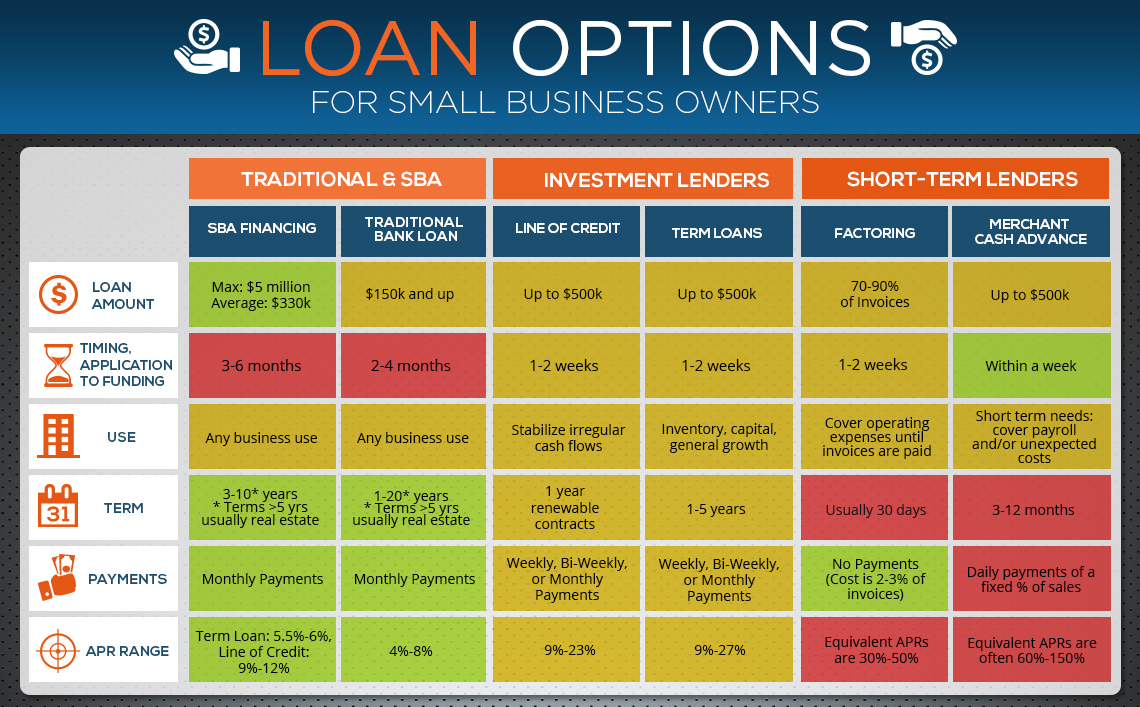
Understanding the true cost of a loan is crucial for making an informed decision. This involves calculating the total amount you will pay over the loan term, including interest payments, fees, and other expenses. By comparing the total costs of different loan options, you can determine the most cost-effective choice.
To calculate the total cost of a loan, you can use the following methods:
- Loan Calculator: Many lenders and financial websites provide online loan calculators that can estimate the total cost of a loan based on the loan amount, interest rate, loan term, and fees.
- Manual Calculation: You can also calculate the total cost manually using the following formula:
Total Cost = Loan Amount + Interest Payments + Fees + Other Expenses
Once you have calculated the total cost of each loan option, you can compare them using a table:
Loan Cost Comparison Table
| Loan Option | Total Cost | Interest Payments | Fees | Other Expenses |
|---|---|---|---|---|
| Option 1 | $12,000 | $6,000 | $2,000 | $4,000 |
| Option 2 | $13,000 | $7,000 | $1,500 | $4,500 |
| Option 3 | $11,500 | $5,500 | $2,500 | $3,500 |
By comparing the total costs of different loan options, you can easily identify the most cost-effective choice that aligns with your financial situation and goals.
Impact on Credit Score
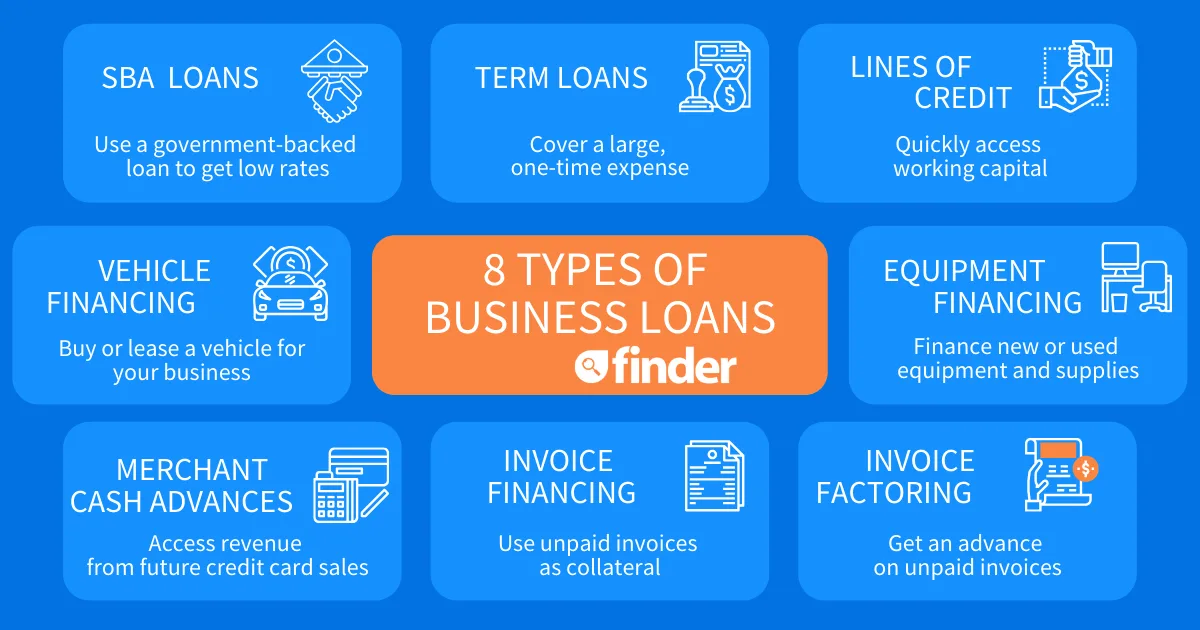
Understanding the potential impact of different loan options on your credit score is crucial. Your credit score reflects your creditworthiness and plays a significant role in determining your eligibility for future loans and credit cards, as well as the interest rates you qualify for. Here’s how loan payments can affect your credit score:
Firstly, making on-time payments is one of the most important factors in maintaining a good credit score. Each missed or late payment is recorded on your credit report and can negatively impact your score. Therefore, it’s essential to choose a loan option that fits your budget and allows you to make timely payments consistently.
Credit Utilization
Your credit utilization ratio, which measures the amount of credit you’re using compared to your total available credit, also affects your credit score. Using a high percentage of your available credit can be seen as a sign of financial stress and can lower your score. Choosing a loan option with a higher loan amount or a shorter repayment period can increase your credit utilization ratio, potentially harming your score.
Credit Mix
Lenders like to see a mix of different types of credit accounts on your report, such as installment loans (e.g., mortgages, auto loans) and revolving credit (e.g., credit cards). Having a diverse credit mix demonstrates your ability to manage various types of credit responsibly and can positively impact your score.
Credit Inquiries, How can I compare different loan options?
When you apply for a loan, the lender will typically run a hard credit inquiry, which can temporarily lower your credit score. Multiple hard inquiries in a short period can raise red flags for lenders and may negatively affect your score. Choosing a loan option that minimizes the number of hard inquiries can help protect your credit score.
Suitability Assessment
Assessing the suitability of loan options requires a comprehensive evaluation of the borrower’s financial situation, goals, and risk tolerance. By considering these factors, borrowers can make informed decisions that align with their specific needs and circumstances.
The following framework provides a structured approach to assess loan suitability:
Borrower’s Financial Situation
- Income: Stable income is crucial for loan repayment. Assess the borrower’s income sources, amount, and stability.
- Debt-to-income ratio (DTI): DTI measures the percentage of monthly income allocated to debt payments. Lenders use DTI to evaluate a borrower’s ability to manage additional debt.
- Credit history: A good credit history indicates a borrower’s responsible financial behavior and creditworthiness.
- Assets and liabilities: Consider the borrower’s assets and liabilities to determine their overall financial health.
Borrower’s Goals
- Loan purpose: Determine the specific purpose of the loan, such as debt consolidation, home purchase, or business expansion.
- Loan term: Consider the desired loan term and how it aligns with the borrower’s financial goals and repayment capacity.
- Repayment schedule: Evaluate the repayment schedule and ensure it aligns with the borrower’s cash flow.
Borrower’s Risk Tolerance
- Interest rate risk: Assess the borrower’s tolerance for interest rate fluctuations, especially for variable-rate loans.
- Default risk: Consider the borrower’s ability to withstand potential financial setbacks and the consequences of loan default.
- Collateral risk: Determine the borrower’s willingness to provide collateral for the loan and the potential risks associated with collateral.
By considering these factors, borrowers can develop a comprehensive understanding of their financial situation, goals, and risk tolerance. This assessment provides a solid foundation for comparing and selecting loan options that are most suitable for their specific needs.
Finish your research with information from How much interest will I pay on a loan?.
Outcome Summary: How Can I Compare Different Loan Options?
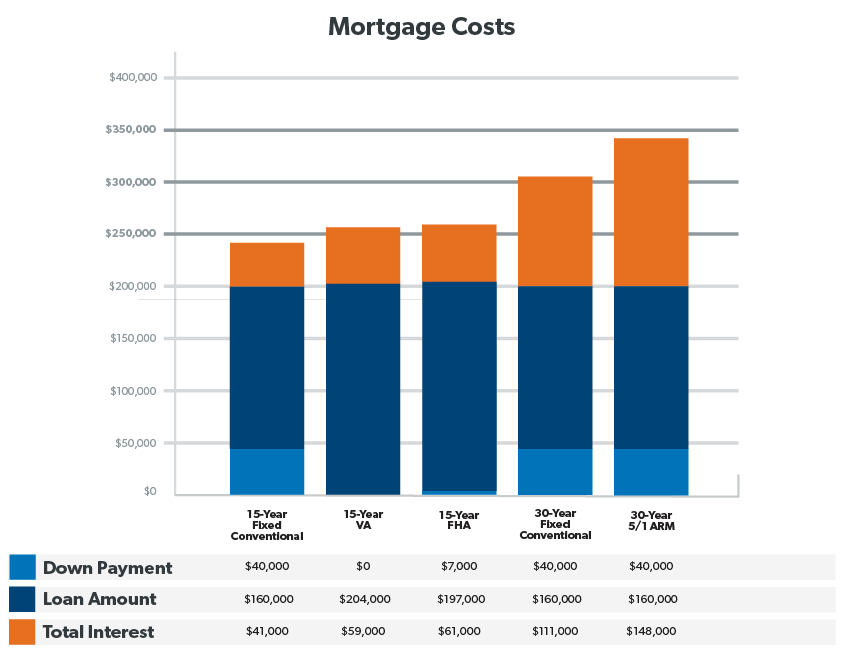
The content of the concluding paragraph that provides a summary and last thoughts in an engaging manner.
FAQ Insights
What factors should I consider when comparing different loan options?
Interest rates, loan terms, fees, repayment options, and impact on credit score.
How can I calculate the total cost of a loan?
Add up the interest payments, fees, and other expenses over the loan term.
How can I assess the suitability of a loan option for my financial situation?
Consider your income, expenses, debts, and financial goals.