How to calculate compound interest on a loan – When it comes to calculating compound interest on a loan, it’s crucial to understand the formula and variables involved. This comprehensive guide will delve into the intricacies of compound interest, exploring its impact on loan calculations and providing practical tips for using Excel and financial calculators to make informed decisions.
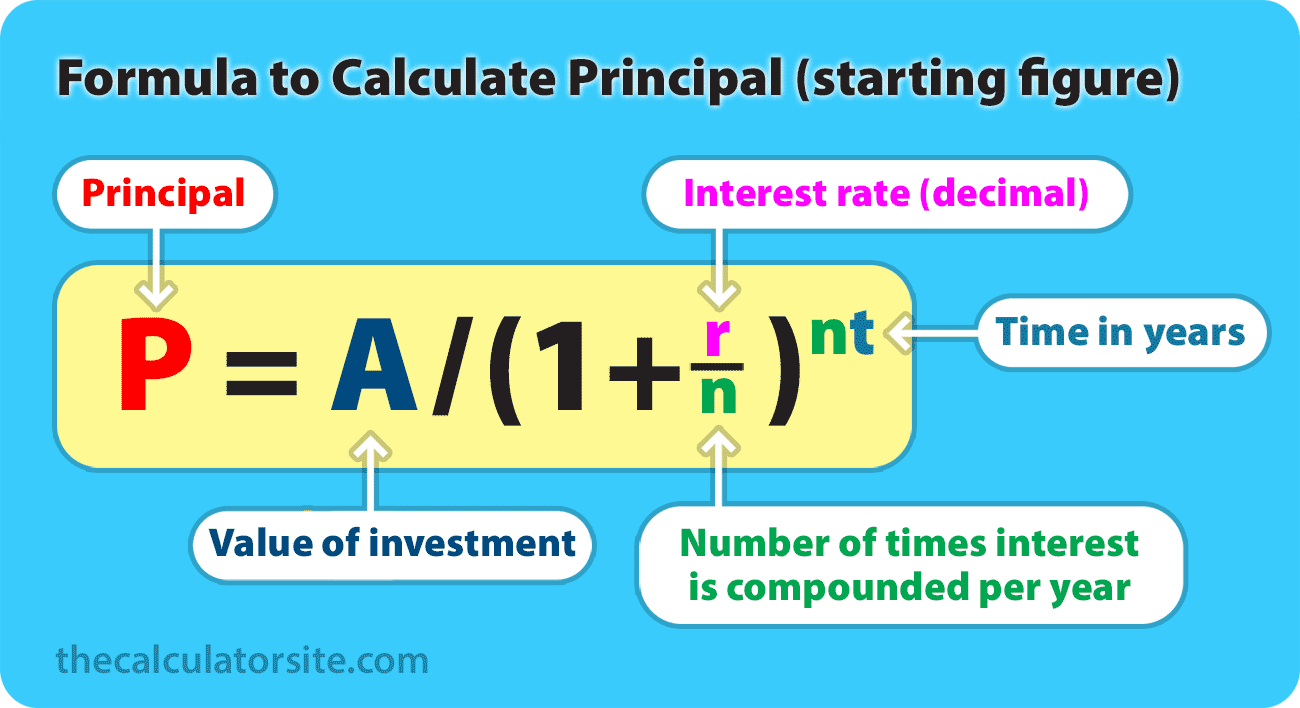
The formula for compound interest, A = P(1 + r/n)^(nt), takes into account the principal amount, interest rate, compounding frequency, and time period. By understanding these variables, you can accurately calculate the total interest paid over the life of the loan.
Formula and Variables
Calculating compound interest on a loan involves using a specific formula. This formula takes into account several variables, including the principal amount borrowed, the interest rate, and the time period over which the interest is compounded.
The formula for compound interest is:
A = P(1 + r/n)^(nt)
where:
- A is the future value of the investment/loan, including interest.
- P is the principal investment/loan amount.
- r is the annual interest rate in decimal form.
- n is the number of times that interest is compounded per year.
- t is the number of years the money is invested or borrowed for.
For example, if you borrow $1,000 at an annual interest rate of 5%, compounded monthly (n=12), for 5 years (t=5), the future value of the loan would be:
A = 1000(1 + 0.05/12)^(12*5) = $1,283.36
Impact of Compounding Frequency
The frequency of compounding significantly influences the total interest paid over the life of a loan. More frequent compounding results in higher interest charges due to the “interest on interest” effect.
As the compounding frequency increases, the interest earned in each compounding period becomes smaller. However, the number of compounding periods also increases, leading to a greater cumulative effect over time.
Illustration
| Compounding Frequency | Total Interest Paid |
|---|---|
| Annually | $1,250 |
| Semi-annually | $1,275 |
| Quarterly | $1,295 |
| Monthly | $1,310 |
| Daily | $1,315 |
The table above demonstrates the impact of compounding frequency on the total interest paid for a $10,000 loan with a 5% interest rate and a 10-year term.
When investigating detailed guidance, check out How to calculate GPA for transfer students now.
Applications in Loan Calculations
Compound interest calculations are crucial in loan calculations, as they provide a comprehensive understanding of the total cost of borrowing and the impact on monthly payments and the overall repayment schedule.
Compound interest affects loan calculations in several ways:
Total Cost of Loan
Compound interest accumulates over time, leading to a higher total cost of the loan compared to simple interest. This is because the interest is calculated not only on the principal amount but also on the accumulated interest from previous periods.
Monthly Payments
Compound interest affects the monthly payments by increasing the amount of interest that is added to the principal balance each month. As a result, the monthly payments will be higher than with simple interest.
Repayment Schedule, How to calculate compound interest on a loan
Compound interest impacts the repayment schedule by extending the period over which the loan is repaid. This is because the higher monthly payments and total cost of the loan require a longer repayment period.
Calculating Compound Interest Portion of Loan Payment
To calculate the compound interest portion of a loan payment, follow these steps:
- Calculate the periodic interest rate: Divide the annual interest rate by the number of compounding periods per year.
- Calculate the interest for the period: Multiply the periodic interest rate by the current principal balance.
- Subtract the principal repayment from the total payment: The principal repayment is the amount of the payment that goes towards reducing the principal balance.
The difference between the total payment and the principal repayment represents the compound interest portion of the loan payment.
Excel and Financial Calculators: How To Calculate Compound Interest On A Loan

For quick and accurate compound interest calculations, Excel and financial calculators offer convenient and accessible solutions. These tools simplify the process, allowing you to analyze different loan scenarios and make informed decisions.
Using Excel
In Excel, use the formula =FV(rate, nper, pmt, [pv], [type]), where:
rate: Annual interest rate as a decimal (e.g., 5% = 0.05)nper: Number of compounding periodspmt: Periodic payment (usually 0 for loan calculations)pv: Present value (optional; default is 0)type: 0 for end-of-period compounding (default), 1 for beginning-of-period compounding
Using Financial Calculators
Financial calculators often have dedicated buttons for compound interest calculations. Enter the following variables:
- Loan amount (present value)
- Interest rate
- Number of compounding periods
- Compounding frequency
Tips
- Use the correct compounding frequency to match the loan terms.
- Analyze different scenarios by varying the interest rate, loan amount, or compounding frequency.
- Compare loan options to identify the most cost-effective choice.
Closing Notes
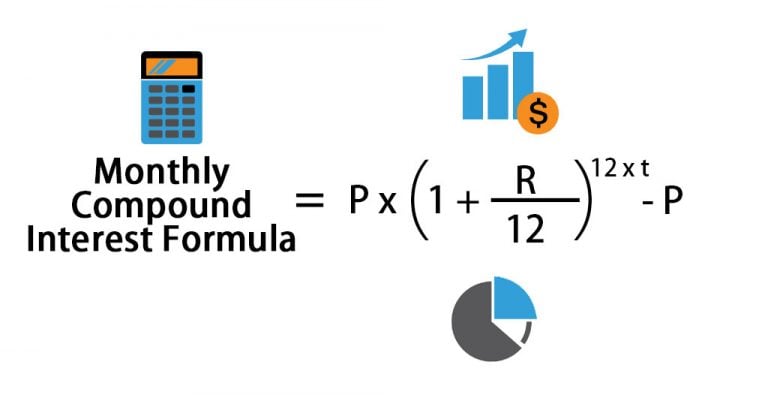
In conclusion, calculating compound interest on loans is essential for making informed financial decisions. By understanding the formula, variables, and impact of compounding frequency, you can effectively assess loan costs and repayment schedules. Utilizing Excel or financial calculators simplifies these calculations, empowering you to analyze different loan scenarios and make choices that align with your financial goals.
FAQ Section
What is the formula for compound interest?
A = P(1 + r/n)^(nt)
How does compounding frequency affect interest charges?
More frequent compounding leads to higher interest charges.
How can I use Excel to calculate compound interest?
Use the FV function: =FV(rate, nper, pmt, [pv], [type])